In elite sport, the difference between a strong competitor and a champion is often a fraction of a second. The UK’s life sciences environment finds itself in much the same position: world-class at discovery, now chasing the gains that turn scientific strength into companies that scale, and stay, at home.
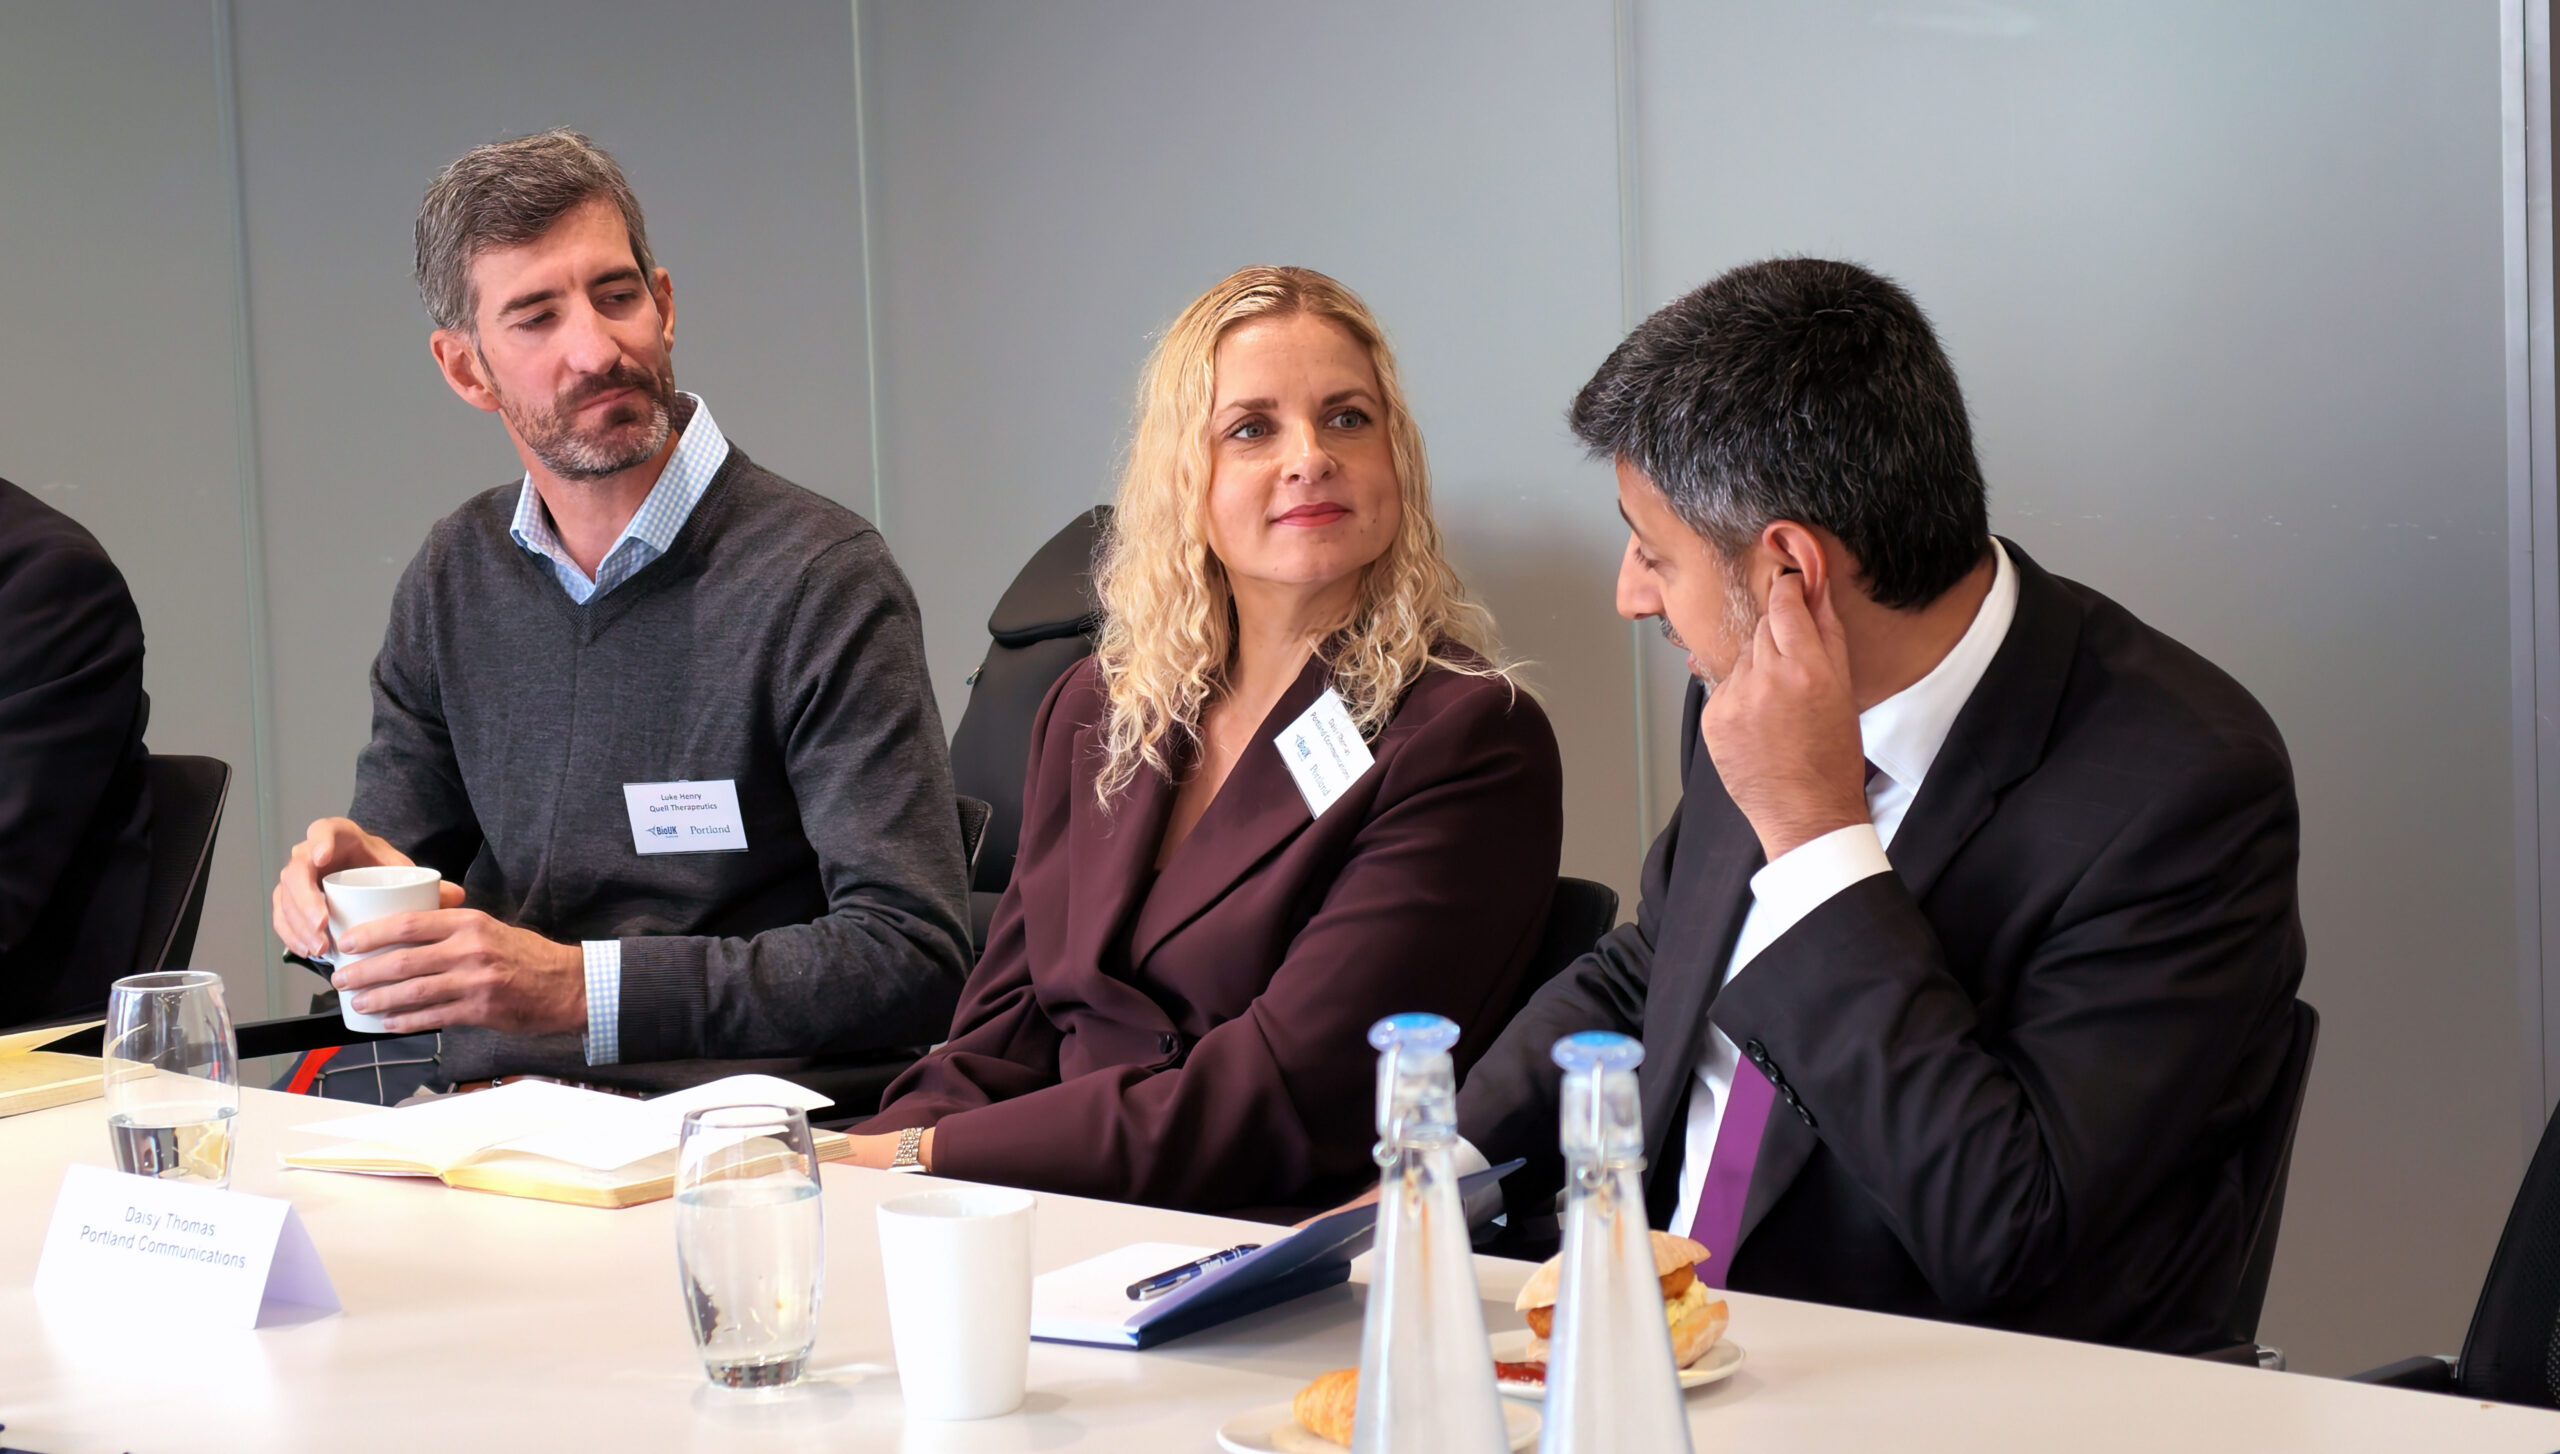
On 10 September 2026, Portland’s Healthcare and Life Sciences team, in partnership with BioUK, brought together biotech leaders and policy experts for a breakfast roundtable on a challenge that sits at the heart of the UK Government’s growth ambitions: how smaller and mid-size biotechs can move from start-up to scale-up without being pulled overseas at the very moment they begin to succeed.
We were joined by two speakers:
- Dr Zubir Ahmed MP, drawing on his experience as a life sciences minister and his perspective on how government can better back the sector
- Luke Henry, Chief Business Officer and Chief Operating Officer at Quell Therapeutics, sharing what it looks like from inside a UK-heritage biotech that spun out of a British university and is now navigating the realities of scaling
What emerged across the conversation was a strikingly consistent diagnosis. The UK’s problem is not a shortage of science, talent or ideas. It is a persistent difficulty in converting world-class discovery into companies that can scale and stay in the UK. To borrow the morning’s most memorable image, the country already has the makings of an elite athlete – the race is being lost in the final stretch.
A world-class start, an uncertain middle
The UK’s foundational strengths are not in doubt. It has outstanding scientists, leading universities and a proven ability to spin promising companies out of its research base. Genomics, CAR-T cell therapies and personalised medicines are all emerging from exactly the kind of smaller companies that make up the majority of the sector – a point, attendees noted, that is well understood at the most senior levels of government.
The difficulty comes at the transition to meaningful growth. It is not simply a question of how much capital goes in at the start, but of how support is sustained as a company matures. Too often, the large cheques arrive from the United States, the natural listing venue becomes the NASDAQ, and a UK float is never seriously considered. The result is a familiar pattern: British-backed science, scaled elsewhere.
Capital, and the culture of risk
Beneath the funding gap sits a deeper question about appetite for risk. Speakers reflected that investors in the US and in fast-moving markets such as China and India are more willing to reward bold, high-risk bets, and that this is as much a cultural difference as a financial one. R&D tax credits were singled out as critical infrastructure for an innovative sector, as was the recognition that a lot of senior executive talent sits primarily in the US. Encouraging companies to stay is welcome – but it must be matched by an environment that rewards those willing to take a risk and back them.
The NHS paradox: access, pricing and pull-through
Nowhere was the tension between promise and pull-through clearer than in the discussion of the NHS. The UK is a superb place to run clinical trials, with increasingly fast set-up times due to the UK Government’s 150-day target, patients can gain early access to novel therapies. Yet speakers described how that access too often stops at the trial’s edge: a company can treat UK patients during a study, only to find there is no clear commercial or NHS route once a medicine is approved – meaning the UK is not counted as part of the core market.
The paradox is that the NHS could be one of the UK’s greatest competitive advantages rather than a barrier. Its scale offers something the fragmented US system cannot: the potential for a single front door for research, anchored in the NIHR, that makes it simple to open and run studies at pace. There is also a powerful soft-power dimension: when the UK chooses to pay for a medicine, others often follow, giving the country influence well beyond its size.
Regulation as a national strength
If there was a note of clear optimism, it was on regulation. The way the MHRA supports scientific progress while safeguarding patient safety is respected internationally, and initiatives such as the Innovative Licensing and Access Pathway (ILAP) were held up as successes to build on. In a global environment where speed and cost increasingly drive decisions about where to develop, a proportionate, world-class regulatory system is a real differentiator – and one the UK should protect and extend.
Marginal gains
Which returns us to the elite athlete. The raw ability is there; competitiveness now comes down to the small margins – the details that shave the last half-second off a performance. The UK will never be the cheapest place to develop a medicine, nor the largest market, and it does not need to be.
But by connecting its science, its regulation, its NHS and its convening power more deliberately, it can offer something few others can. The ingredients for success are already in place; what the sector needs now is the confidence – and the coordination – to assemble them, so that companies born out of British science can grow and stay at home.
For smaller biotechs in particular, helping to shape the policy environment they depend on has rarely mattered more.
To find out more about how Portland’s Healthcare and Life Sciences practice can support your organisation, please contact Daisy Thomas, Managing Partner and Head of Healthcare and Life Sciences.